

Why AI May Finally Solve Insurance's Persistency Problem
It was 3:00 PM on September 8, the first day of school.
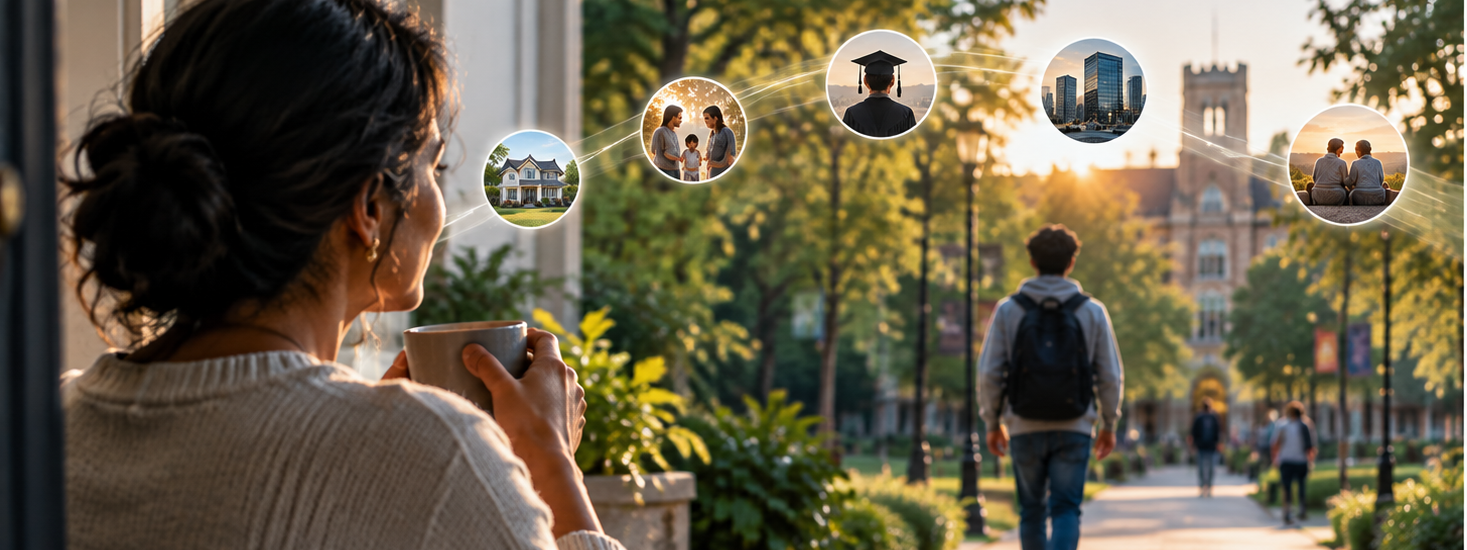
For more than 12 years, I had developed a routine around that moment. Around 3 PM, almost without thinking, I would look out the window expecting my son to walk through the door after school.
This year, he did not.
For a brief moment, I felt anxious. Then I remembered: he was not at school anymore. He had left for university.
It was a small moment, but it reminded me how powerful habits can be. Twelve years of repeated behavior had created an expectation that continued even after the circumstances had changed.
And it made me think about persistency in life insurance.
Customers develop financial habits. Advisors build relationships. Payment behaviors become established. The value of a product is reinforced, or weakened, through ongoing engagement. Over time, these patterns help determine whether a policy remains in force or eventually lapses.
But people's lives do not stand still. Families grow. Careers change. Financial priorities shift. Affordability changes. What looked like a highly persistent customer when a policy was issued may look very different two or five years later.
The problem is that insurers often see the result after the underlying behavior has already changed. By the time persistency appears on a 13-month, 25-month or 61-month dashboard, the outcome may already have been determined. The lapse has happened. The customer has left. The economic and protection value has been lost.
What if life and annuity insurers could identify those signals earlier? What if they could understand persistency risk before a policy is issued, monitor how that risk changes throughout the policy lifecycle and intervene early enough to influence the outcome?
I believe this is one of the most compelling applications of AI in life and annuity insurance today.
Persistency should be managed, not simply measured
Having spent more than two decades in insurance across technology, operations and business transformation, I have seen insurers invest significantly in underwriting modernization, customer experience, distribution, analytics and digital servicing.
Yet persistency is still often treated primarily as a reporting metric.
That matters because a lapse affects much more than a single policy. It can affect future premium revenue, customer lifetime value, acquisition-cost recovery, advisor productivity, embedded value, shareholder returns and, importantly, whether customers retain the protection they originally purchased.
The opportunity is therefore bigger than improving a persistency dashboard. It is moving from measuring persistency to actively managing it.
From automation to intelligence
Insurers have already made considerable progress.
Automated premium reminders, SMS and email notifications, grace-period communications, advisor alerts and outbound retention programs can all create value. They can improve efficiency and help recover policies that might otherwise lapse.
But these interventions are largely reactive. The reminder is generated because a payment has already been missed. Outreach begins because the customer has entered a known risk state. Intervention happens after the warning signal becomes visible.
AI creates the possibility of asking a different question. Instead of "How do we recover a customer who may lapse?", we can ask "How do we identify and potentially prevent that lapse months earlier?"
That is an important shift from automation towards intelligence.
Persistency is a decision problem
Many of the most visible applications of AI in insurance focus on underwriting, claims processing, document handling, customer service and contact centers.
Persistency presents a somewhat different challenge. Persistency is not primarily a workflow problem. It is a decision problem.
It is influenced by multiple, changing factors: customer circumstances, product fit, affordability, advisor and distribution characteristics, payment behavior, engagement and life events.
These factors do not operate independently, and they continue to evolve throughout the customer relationship. For AI-enabled persistency management to be useful, insurers need to connect signals across several areas:
Customer: financial profile, affordability, family circumstances and life stage.
Product: coverage, premium, complexity and product fit.
Distribution: advisor, agency and channel performance.
Behavior: engagement, interactions, purchase journey and payment patterns.
Servicing: missed payments, service requests, grace-period usage and policy changes.
Life events: where appropriate and subject to privacy, consent and regulatory requirements, changes in family, employment, retirement or financial circumstances.
Individually, these signals tell only part of the story. Combined, they can create a richer picture of persistency risk and help explain not only who may lapse, but why.
Persistency can start before a policy lapses
Persistency is often considered a servicing problem.
In reality, some of its drivers can emerge much earlier, including during underwriting and the original purchase journey.
Traditional underwriting appropriately evaluates mortality, morbidity, financial eligibility and risk selection. Long-term persistency can also be influenced by product fit, affordability, customer behavior, advisor quality, distribution characteristics, life stage and financial habits.
This creates an opportunity to think differently about the quality of new business. A sale creates revenue. A policy that remains appropriately in force over time creates longer-term value.
Distribution quality therefore matters as well. Persistency patterns across advisors, agencies, brokers, IMOs, bancassurance networks and direct channels can help insurers understand where business is not simply being written, but sustained.
The objective is sustainable production, not production alone.
Prediction is only the beginning
Identifying potential lapse risk is valuable, but a risk score alone is not enough.
An underwriter does not want to be told simply that "the AI says this customer may lapse." An advisor cannot act effectively on an unexplained number. And business, risk and technology leaders need to understand the basis for consequential decisions.
For AI to become a trusted business tool, the insight needs to answer three questions:
Why has this customer received this assessment?
Which factors are contributing most to the outcome?
What actions could potentially improve that outcome?
That leads to a simple model for AI-enabled persistency:
Predict. Explain. Act.
Predict where persistency risk may be emerging. Explain the factors contributing to that risk. Act early enough for an appropriate intervention to have a chance of influencing the outcome.
This is the difference between prediction and prevention.
For example, instead of simply identifying elevated lapse risk, an explainable approach could identify that affordability pressure has increased, engagement has declined or payment behavior is changing, and then help determine whether advisor outreach, customer education, payment options or another intervention may be appropriate.
Different customers require different interventions
This matters because two customers can arrive at very different persistency outcomes for very different reasons.
A customer with stable income, an appropriate product, manageable premiums, positive engagement and a strong advisor relationship may demonstrate relatively low lapse risk. In that situation, the objective may simply be to reinforce an already healthy relationship through relevant communication and servicing.
Another customer may have a more complex product, increasing affordability pressure, lower engagement or distribution characteristics associated with weaker persistency.
The value is not simply identifying that the second customer carries greater risk. It is understanding what is driving that risk and what could potentially be done about it.
That is where explainability becomes commercially useful. It allows insurers to move from a generic retention program towards more informed and potentially more relevant intervention.
Distribution quality matters more than we think
Persistency challenges are often attributed primarily to customers. But distribution quality can be equally important.
The wrong customer with the right product can lapse. The right customer with the wrong product can lapse. An advisor focused primarily on the initial sale rather than long-term suitability can unintentionally contribute to future persistency challenges.
Looking at patterns across advisors, agencies, IMOs, brokers, bancassurance networks and direct-to-consumer channels can therefore add another dimension to persistency management.
It can help insurers move beyond measuring production towards understanding sustainable production. A sale matters. A customer relationship that remains valuable and appropriate over time matters more.
Persistency must be managed throughout the lifecycle
Underwriting is only the beginning.
Customers continue to evolve. They get married. They have children. They change jobs. They approach retirement. They encounter new financial realities. Their relationship with the insurer evolves as well.
Historically, insurers often react when a payment is missed, a policy enters a grace period, engagement falls or a customer asks to cancel.
By then, the relationship may already be deteriorating. The larger opportunity is to identify emerging risk earlier and determine when an intervention may be appropriate.
That does not mean every change should trigger an action. Nor does it mean that AI should make every decision. It means giving insurers and advisors better information earlier in the lifecycle, when there may still be an opportunity to support the customer and influence the outcome.
The objective is to move from reactive firefighting towards proactive prevention.
The NTT DATA perspective
This thinking is also informing our work at NTT DATA around AI-enabled persistency for life and annuity insurers.
NTT DATA's Persist AI brings together customer, product, advisor, behavioral and distribution factors to help estimate future lapse risk.
Importantly, the objective is not simply to produce another score. The approach is designed to explain the factors contributing to the prediction and recommend actions that may help improve the outcome.
Across the policy lifecycle, this creates an opportunity to identify emerging risks earlier and support more personalized interventions before the relationship reaches the point where traditional persistency measures would flag the problem.
The principle is straightforward:
Predict the risk. Explain what is driving it. Act early enough to influence the outcome.
Technology should support the business decision rather than simply generate another score.
From predicting lapses to preventing them
For L&A insurers, persistency has traditionally been something measured after the fact. AI creates an opportunity to manage it differently: predicting risk earlier, explaining why it exists and helping insurers act before a lapse becomes inevitable.
For me, that is what makes this use case particularly meaningful.
Persistency is not ultimately about policies. It is about people.
It is about helping families maintain the protection they purchased. It is about helping advisors build deeper and more trusted relationships. And it is about helping life and annuity insurers create sustainable long-term growth.
The question is no longer simply whether AI can predict a lapse. The more important question is "Can AI explain the risk and help insurers act before the outcome is decided?"
That may be where one of the next major opportunities for AI in life and annuity insurance emerges.
Related content


Post / Governing Agentic AI in Insurance: From Principles to Operating Model
How carriers can embed trust, control, and accountability into AI-driven decision workflows.

Post / The next frontier of insurance AI: workplace orchestration
Insurance advantage will come from building an agentic Workplace where AI and people redesign how underwriting and claims work gets done.

Post / AI’s Sweet Spot with the GenAI Scorecard
A comprehensive scorecard helps organizations to evaluate the performance and impact of GenAI solutions regularly.


Subscribe to Our Newsletter
Get the latest insights about Global solutions for leading insurers on your email